Overview
Why might a Kenyan business need US dollars to pay a supplier in Ghana?
The order is agreed, but the payment has another journey to make. The buyer earns Kenyan shillings; the supplier needs Ghanaian cedis. Depending on the route, the provider may convert shillings into dollars, then dollars into cedis. Each conversion can include a charge built into the exchange rate. Transfer fees and intermediary deductions may add to the cost. Currency availability, customer checks and banking hours can affect when the money arrives. For a small business, that uncertainty can squeeze margins, delay stock and leave cash unavailable for the next order. [19, 32]
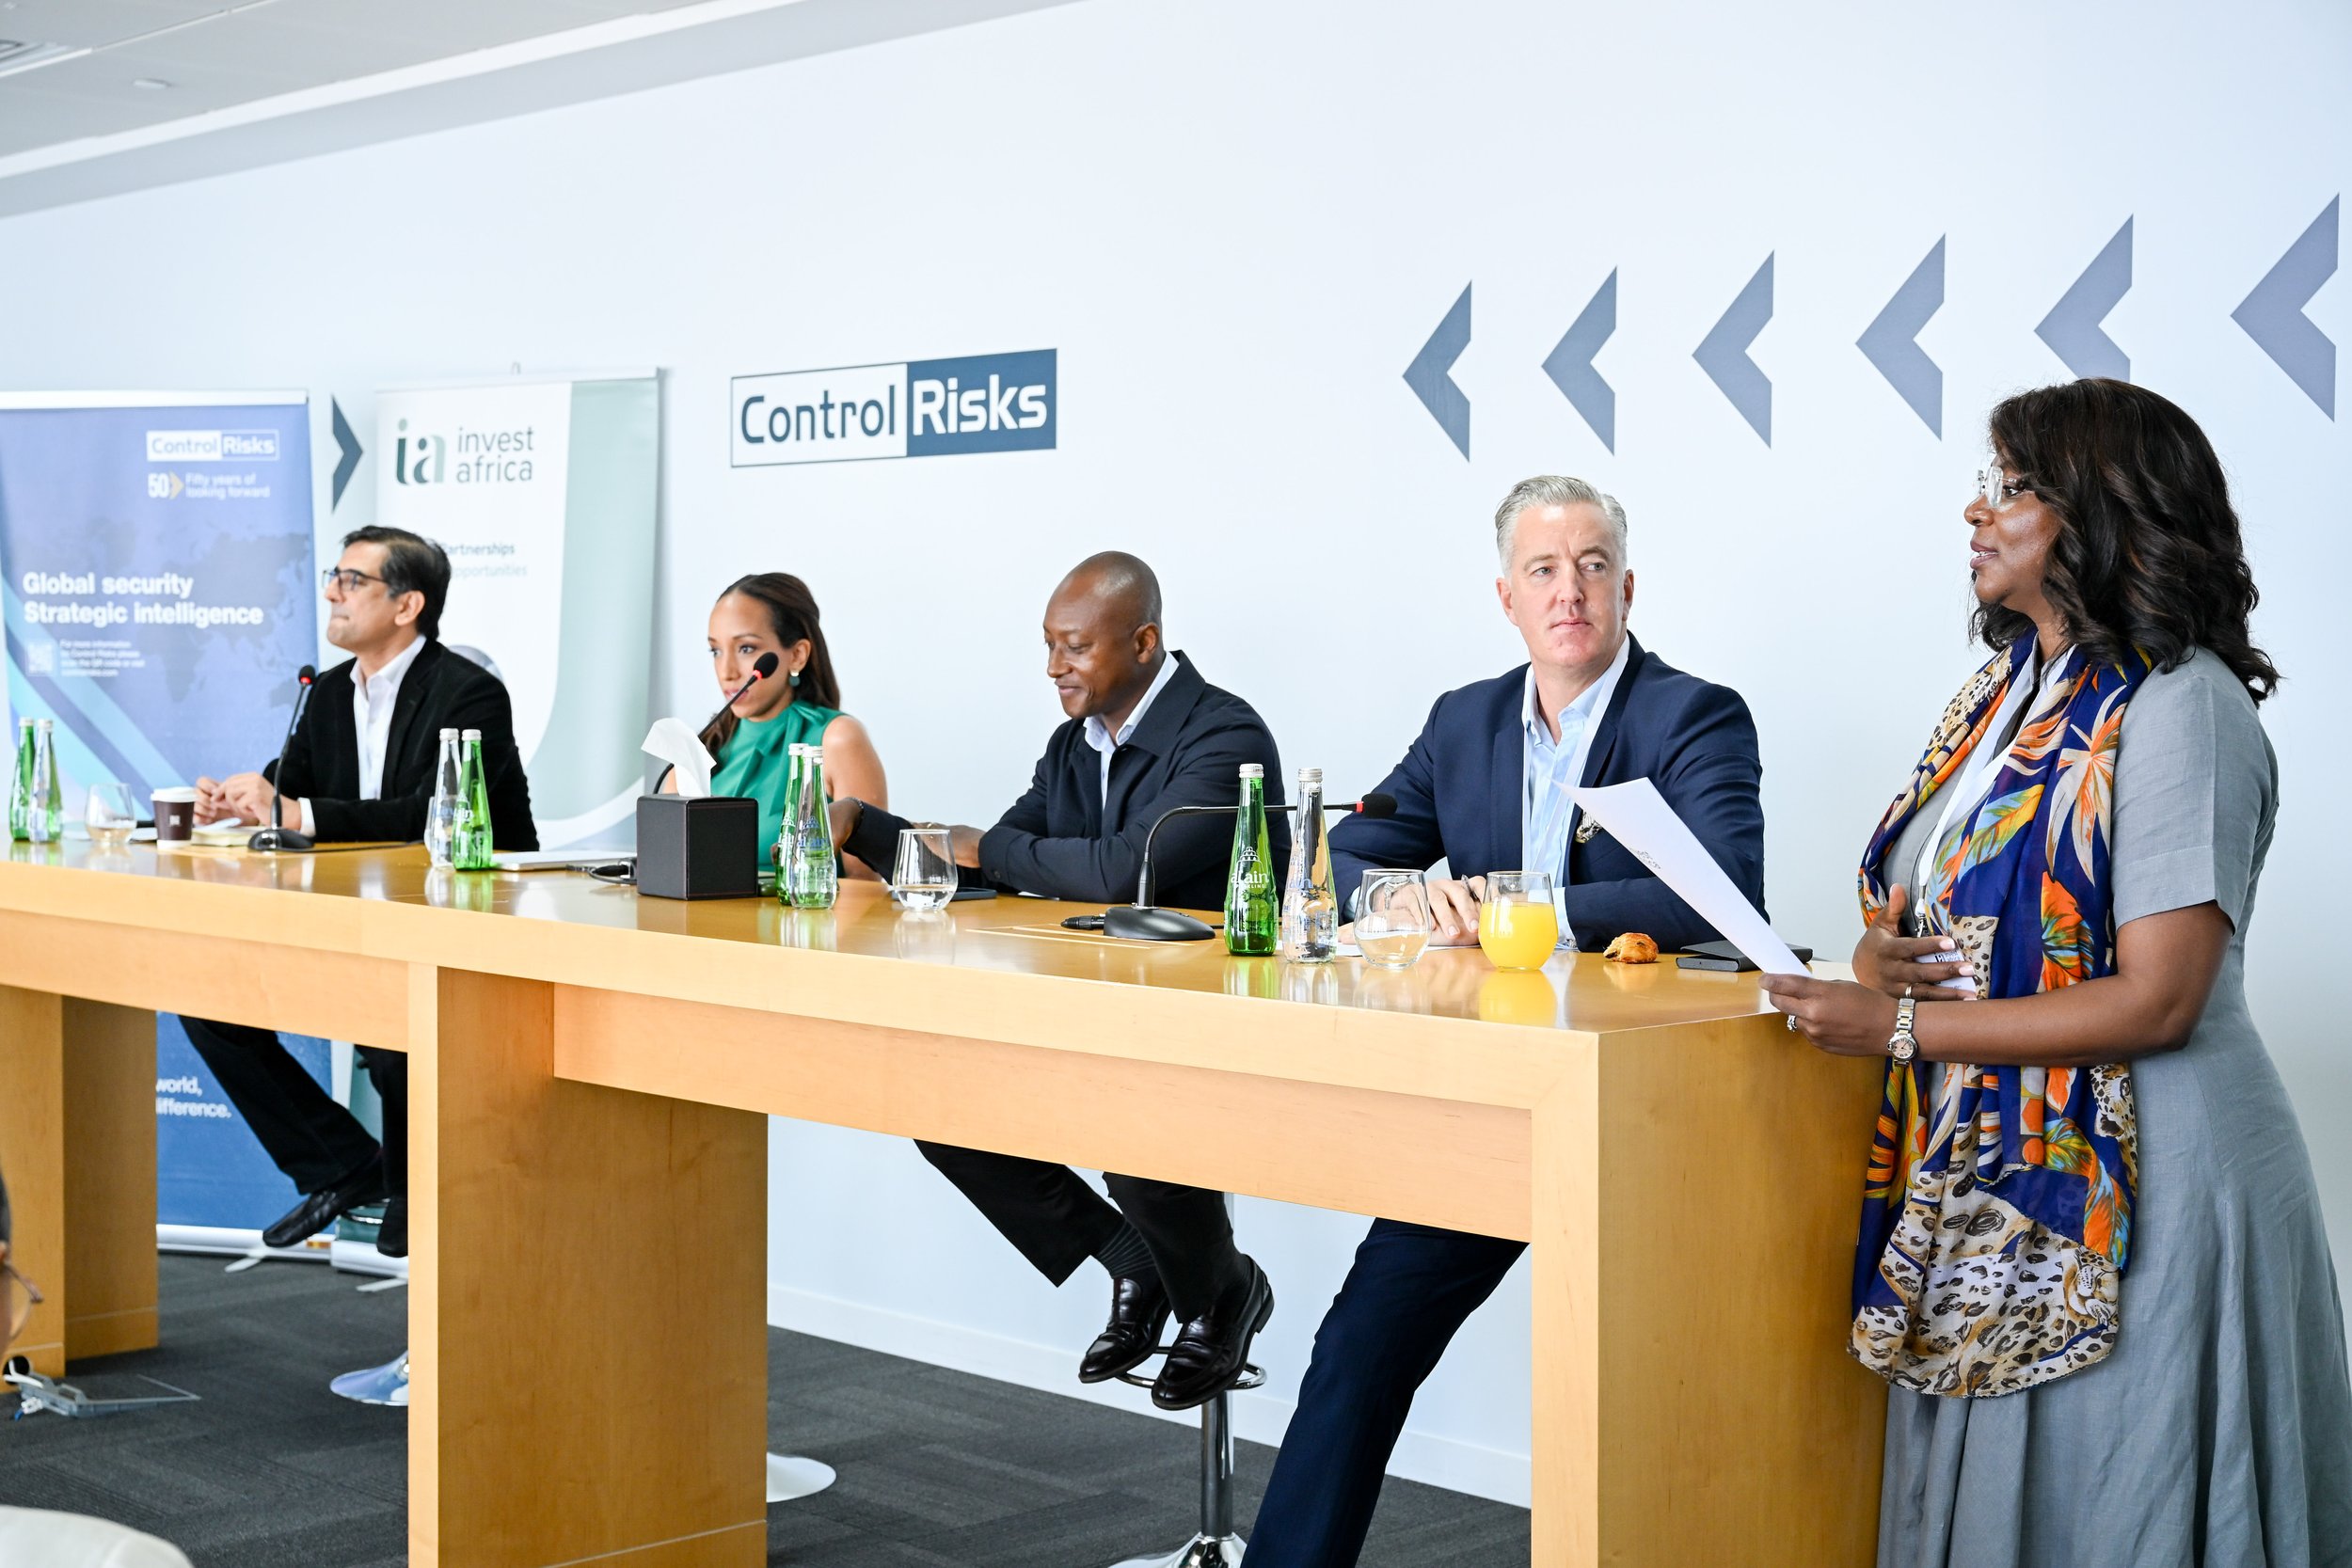
Making cross-border commerce simpler, faster and more affordable was the central goal of the Invest Africa member event in Dubai, hosted by Control Risks Middle East and Africa. Connecting payments, foreign exchange and finance can reduce the cost and complexity of doing business—and bring more people into trade. [1]
Momentum is visible. African mobile-money transactions reached USD 1.4 trillion in 2025, up 27%. In Sub-Saharan Africa, adult account ownership rose from 49% in 2021 to 58% in 2024. Oui Capital’s indicative Africa outlook points to USD 1 trillion by 2035, including estimated informal remittance flows. [3, 28, 29]
Seven takeaways connect that progress to everyday business needs: simpler local-currency payments; broader financial inclusion; consent-based records that help SMEs demonstrate creditworthiness; services supporting the full trading cycle; closer cooperation between providers and policymakers; measures of cost, reliability, credit access and repeat trade; and informed decisions about doing business across Africa.
AXIAN’s mobile-finance networks, Verto’s business payments and currency services, and Vault22’s connected financial information illustrate different contributions. Control Risks adds market knowledge and risk perspective. The desired outcome is practical: simpler processes, faster payments and lower total costs, giving businesses greater confidence to place the next order.
The panel: Bilal Bajwa, Chief Product Officer, AXIAN Group; Helen Ghebreluul, Country Head, UAE, Verto; and Benito Mable, Founder and CEO, Vault22. Moderated by Tom Griffin, Partner, Control Risks. [1]
PROGRESS IN FIGURES
The scale of the opportunity
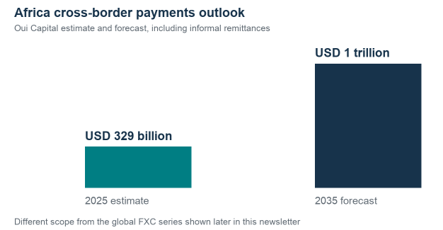
USD 329 billion to USD 1 trillion Oui Capital’s estimate for 2025 and forecast for 2035. Its Africa report includes estimated informal remittance flows; this is an indicative outlook, not a forecast of intra-African trade alone. [28]
USD 1.4 trillion Mobile-money transactions across Africa in 2025, up 27% and representing 66% of global transaction value, according to GSMA. These include domestic payments, not just cross-border transfers. [29]
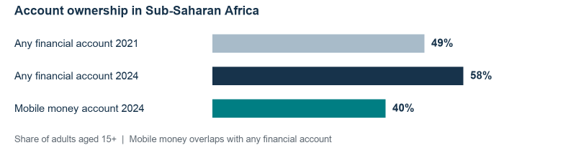
World Bank Global Findex 2025; adults aged 15+, surveyed in 2024. Mobile money is included within overall account ownership. The charts measure different markets and should not be added together. [3, 4]
The global context: FXC Intelligence estimates business and consumer cross-border payments at USD 44 trillion in 2025, excluding wholesale financial-market payments, reaching USD 67.3 trillion by 2033. [2]
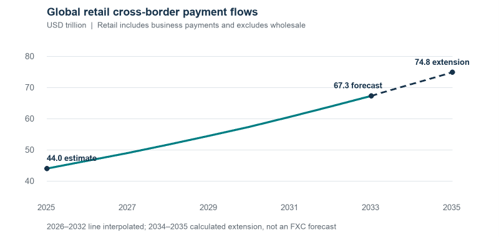
The dotted section is a calculated extension, not an FXC forecast; the intervening line is interpolated. Definitions differ from Oui Capital’s Africa outlook. [2, 28]
SEVEN TAKEAWAYS
Connecting trade and financial inclusion
1. Making local currencies work for trade
For the Kenyan buyer and Ghanaian supplier, exchange rates, transfer charges and intermediary deductions affect the final cost. Delays can hold up goods and working capital. A useful quote states the buyer’s total cost, the supplier’s final receipt and expected arrival time. [32]
The opportunity: Strengthen local-currency payment routes, improve access to foreign exchange and connect domestic payment systems.
PesaLink’s February 2026 connection with PAPSS supports local-currency payments into Kenya. Verto offers multi-currency accounts, currency exchange and payments in markets including Kenya, Nigeria, Tanzania and South Africa. It reported processing over USD 25 billion annually in October 2025. Specific routes remain provider-dependent. [8, 9, 11, 26]
PAPSS reports approximately 1,000% growth in transaction numbers between comparable 2025 and 2026 periods, without disclosing absolute counts or exact dates. [30]
Local-currency payments can reduce customers’ need to buy dollars. PAPSS still includes a hard-currency settlement step between institutions, so foreign exchange remains part of completing the transaction. [19]
2. Extending financial inclusion into everyday commerce
Financial inclusion is advancing. In Sub-Saharan Africa, adult account ownership rose from 49% in 2021 to 58% in 2024; 40% of adults held a mobile-money account in 2024. The next step is making those accounts useful for earning, trading, saving and borrowing. [3, 4]
The opportunity: Connect wallets with banks and merchants, with affordable services that reach women-led firms and underserved communities.
AXIAN’s Mixx and MVola operate in Tanzania, Senegal, Togo, Madagascar and Comoros. AXIAN reports 24 million registered mobile-money customers; separately, it reports USD 46 billion in transactions during 2024. Its Mastercard partnership seeks to extend cards and merchant services across these markets. [6, 24]
The next chapter is deliberately inclusive. A programme launched with the African Development Bank in September 2026 aims to bring tailored financial services to 34,000 women-led businesses in Madagascar, Tanzania and Senegal, and training to 25,000 women across all five markets. Its planned reach shows how mobile finance can be paired with the skills and business support entrepreneurs need to grow. [25]
3. Helping SMEs demonstrate their financial strength
A small business may have regular sales but little formal credit history. An attendee’s account of Bilal Bajwa’s remarks highlights a practical issue: cash transactions can leave gaps in the business’s financial record. Verified bank, wallet and invoice records can help lenders see more of its cash flow, with consent and safeguards. [20, 21, 31]
The opportunity: Make business activity easier to demonstrate, supporting responsible access to working capital.
Benito Mable’s discussion emphasised a fuller financial picture, including assets beyond bank records. Vault22’s wider African ambition builds on its established presence in South Africa and the UAE, where it connects personal financial information. The opportunity extends beyond one market: with consent, a portable SME financial record could help lenders assess verified trading activity alongside other financial information. [10, 20, 31, 33]
SEVEN TAKEAWAYS CONTINUED
Turning connected services into business growth
4. Supporting the full trading cycle
Paying a supplier is part of a longer journey: taking orders, buying stock, managing currencies and financing delivery. Connected services can support each stage.
The opportunity: Link payments, financial information and suitable working-capital finance around everyday business needs. AXIAN’s mobile finance, Verto’s payments and currency services, and Vault22’s personal financial insights illustrate different parts of this ecosystem. [6, 9, 10] The attendee account records Helen Ghebreluul’s explanation of how Verto connects businesses to multiple banking partners through one platform, widening their options for services and pricing. [31]
5. Connecting providers and policymakers
Progress depends on cooperation. Ghana’s wallet-to-bank connections, Rwanda’s eKash services and Kenya’s regional payment links show how institutions can make separate services work together. The country table highlights further examples. [11, 12, 15]
The opportunity: Make customer checks, payment standards and data-sharing rules work more consistently across markets, while keeping clear responsibilities and consumer protection.
Clearer requirements help providers build services with confidence. Local permissions and currency availability still determine which payment routes they can offer.
6. Measuring progress through participation and trade
The evidence already shows wider access and greater payment activity. The next measure of success is what people and firms can do with those services. Women remain a priority: World Bank data show account ownership among Sub-Saharan African women at 52.3% in 2024, compared with 64.4% among men. [27]
The opportunity: Track lower total payment costs, faster and more reliable receipt, responsible credit access, participation by underserved firms and repeat cross-border trade.
AXIAN’s transaction activity, Verto’s reported payment volume and Vault22’s account coverage show reach and capability. Tracking customer outcomes alongside them would demonstrate how wider access translates into stronger businesses.
7. Building confidence in doing business across Africa
Better payments are most useful when businesses also understand the markets and partners behind each transaction. Control Risks, the event host, is a strategic intelligence and security firm whose work helps organisations assess opportunities and prepare for uncertainty. [22]
The opportunity: Combine local market knowledge with trusted business relationships and resilient operations, so companies can pursue growth with greater confidence.
Tom Griffin’s emphasis on local knowledge, captured in the attendee reflection, brings this into focus: proximity to a market can change how its risks are understood. Control Risks’ Africa Risk-Reward Index 2026 examines resilience and differences between markets. Its country analysis, business-partner checks, cyber security and continuity planning can help companies assess where and how to expand. [22, 23, 31]
MARKET PROGRESS
Payment innovation across African markets
Countries are taking different routes to more connected payments. These examples show progress in domestic services and regional links; they are not a ranking or confirmation that every cross-border payment route is available.
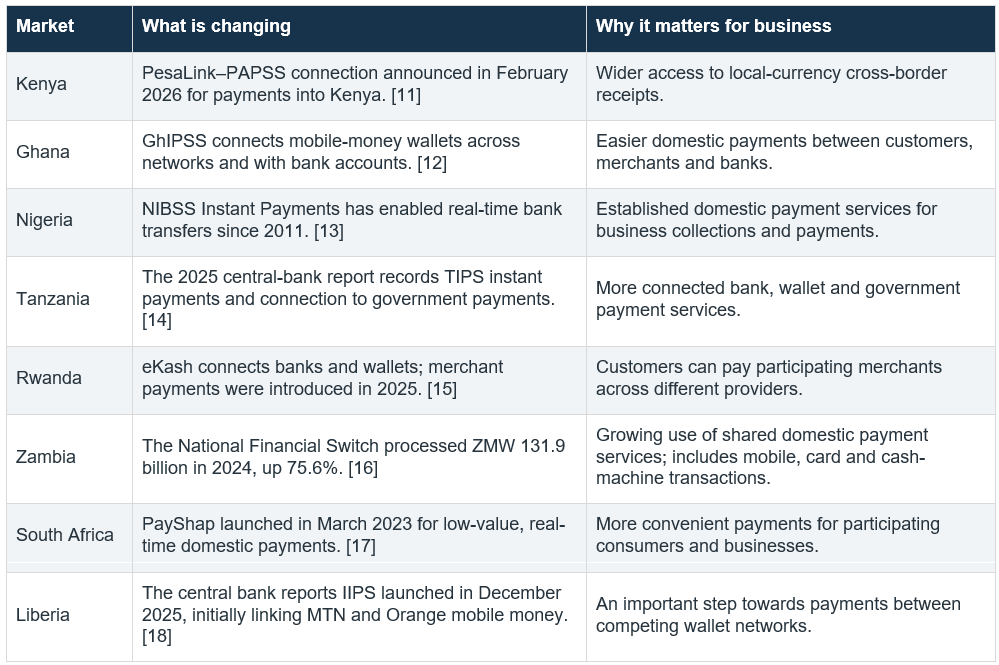
Sources: central banks, government agencies and payment-system operators. Reporting periods and service coverage differ. Domestic connectivity does not by itself provide foreign exchange or international payment access.
From one payment to the next opportunity
Return to the Kenyan buyer and Ghanaian supplier. Success means a simpler payment process, faster receipt and a lower total cost—leaving more cash available to fulfil the next order. With the business’s consent, a clearer trading record can also help a lender understand the enterprise behind the transaction.
The Invest Africa member event, hosted by Control Risks Middle East and Africa, brought these ambitions into one conversation. AXIAN’s mobile reach, Verto’s payment connections, Vault22’s financial insights and Control Risks’ market perspective illustrate the capabilities that can support progress. Practical partnerships and clear rules can help turn them into wider participation: more women-led firms able to grow, more SMEs able to demonstrate their strength, and more businesses able to trade. The shared goal is simpler, faster and more affordable cross-border commerce—and greater opportunity with every order.
SOURCE NOTES
References
Primary research checked on 5 November 2026; payment mechanics refreshed on 6 November. Numbers refer to entries below. Event themes and participation follow the organiser’s notes. Company figures are attributed disclosures, not independently audited impact measures. Dates and definitions differ.
[1] Invest Africa | Enabling Seamless Cross-Border Commerce
Event listing for 3 November 2026. https://www.investafrica.com/invest-africa-events-calendar/enabling-seamless-cross-border-commerce
[2] FXC Intelligence | 2026 Cross-Border Payments Market Sizing Report
March 2026, pp. 3–4. https://s3.dualstack.eu-west-1.amazonaws.com/marketing.fxcintel/newsletter/FXC%20Intelligence%202026%20Cross-Border%20Payments%20Market%20Sizing%20Report.pdf
[3] World Bank | Mobile-Phone Technology Powers Saving Surge in Developing Economies
16 July 2025. https://www.worldbank.org/en/news/press-release/2025/07/16/mobile-phone-technology-powers-saving-surge-in-developing-economies
[4] World Bank | Global Findex Database 2025
2025 edition; survey year 2024. https://www.worldbank.org/en/publication/globalfindex/report
[6] Mastercard | Mastercard and Axian Digibank and Fintech join to advance greater financial inclusion across Africa
[8] Verto | Authorisations and approvals
Live company disclosure; undated. https://verto.co/about-us/company/licences/
[9] Verto | Choosing your model
API documentation; undated. https://docs.verto.co/docs/choosing-your-model
[10] Vault22 | Questions answered
FAQ last updated October 2026. https://vault22.com/faq/
[11] PAPSS | Pesalink and PAPSS unlock cross-border payments in local currencies in Kenya
26 February 2026. https://papss.com/media/pesalink-and-papss-unlock-cross-border-payments-in-local-currencies-in-kenya/
[12] GhIPSS | Mobile Money Interoperability
Live operator service description; undated. https://ghipss.net/our-services/real-time-payments/mobile-money-interoperability/
[13] NIBSS | NIBSS Instant Payments the game changer
Operator account; 2011 development milestone. https://nibss-plc.com.ng/nibss-instant-payments-nip-the-game-changer/
[14] Bank of Tanzania | National Payment Systems Annual Report 2025
2026 publication; 2025 reporting period, section 2.3. https://www.bot.go.tz/Publications/Regular/Annual%20Report/en/2026060211494565.pdf
[15] Rwanda Information Society Authority | Rwanda unveils three transformative innovations at IFF2025
2025 forum; web page undated. https://www.risa.gov.rw/news-detail/rwanda-unveils-three-transformative-innovations-to-advance-digital-finance-and-inclusion-at-iff2025
[16] Bank of Zambia | 2024 National Payment Systems Annual Report
2024 reporting period, section 5.2.5. https://www.boz.zm/2024NPSAnnualReport.pdf
[17] South African Reserve Bank | Press release on the launch of PayShap
[18] Central Bank of Liberia | The Regulator July to September 2025
Web notice 26 December 2025; records 16 December launch. https://www.cbl.org.lr/media/press-releases/regulator-july-sept-2025
[19] PAPSS | How it works
Live system description; undated. https://papss.com/how-it-works/
[20] World Bank | Facilitating SME Financing through Improved Credit Reporting
Publication page; undated. https://www.worldbank.org/en/topic/financialsector/publication/facilitating-sme-financing-through-improved-credit-reporting
[21] World Bank | Data Protection and Privacy
Digital Finance Inclusion resource; undated. https://digitalfinance.worldbank.org/topics/data-protection-privacy
SOURCE NOTES CONTINUED
References continued
[22] Control Risks | Risk consultancy services
Live services directory; undated. https://www.controlrisks.com/our-services
[23] Control Risks | Africa Risk-Reward Index 2026
2026 edition; landing page undated. https://www.controlrisks.com/campaigns/africa-risk-reward-index
[24] AXIAN Group | AXIAN Digibank and Fintech
Live company page; transaction figure relates to 2024; customer figure undated. https://www.axian-group.com/clusters/axian-digibank-fintech/
[25] African Development Bank | AXIAN digital finance programme for women-led businesses
2 September 2026; announced programme targets. https://www.afdb.org/en/news-and-events/press-releases/african-development-bank-and-axian-launch-digital-finance-programme-support-34000-women-led-businesses-africa-96453
[26] Verto | Verto launches in the UAE
6 October 2025; company-reported annual processing scale. https://verto.co/about-us/resources/blog/article/verto-launches-in-the-uae/
[27] World Bank | Sub-Saharan Africa Gender Data Portal
2024 account ownership; live data page. https://genderdata.worldbank.org/en/regions/sub-saharan-africa
[28] Oui Capital | Africa’s Cross-Border Payment Landscape
2025 report, pp. 3–5; includes estimated formal and informal remittances. https://cdn.prod.website-files.com/6479d492e9143e858372843d/6834fe2e5148d34018fb53ef_Africa%27s%20Cross-border%20Payment%20Landscape%20.pdf
[29] GSMA | State of the Industry Report on Mobile Money 2026
2026 report, p. 12; Africa reporting year 2025. https://www.gsma.com/solutions-and-impact/connectivity-for-good/mobile-for-development/wp-content/uploads/2026/04/The-State-of-the-Industry-Report-2026_English.pdf
[30] Afreximbank via APO Group | PAPSS targets accelerated adoption and transaction growth
11 September 2026; issuer press release reproduced by Africa24. https://africa24tv.com/pan-african-payment-and-settlement-system-papss-targets-accelerated-adoption-and-transaction-growth-as-network-expands-across-africa/
[32] Financial Stability Board | Cross-border Payments
Live overview; payment challenges checked 6 November 2026. https://www.fsb.org/work-of-the-fsb/financial-innovation-and-structural-change/cross-border-payments/
[33] Old Mutual | Integrated Report 2024
2024 report, p. 69; wider regional scope of the Vault22 venture. https://eu-assets.contentstack.com/v3/assets/bltdd392fd32dda3ce8/blteca782d28834c8e1/67e3c1db93a8a67a4cbfe1e7/Integrated_Report_2024.pdf
A note on the figures
The 2035 chart value of USD 74.8 trillion extends the annual growth rate implied by FXC’s USD 44 trillion estimate for 2025 and USD 67.3 trillion forecast for 2033. It is an illustration, not a published forecast. Calculation: 67.3 × (67.3 / 44)^(2/8).
Mobile-money totals include domestic transactions and repeated movements of funds. World Bank inclusion figures count adults; GSMA account figures count accounts. Country examples use different dates and definitions and do not measure relative market performance.
This newsletter is a synthesis of the member discussion and supporting research, not a verbatim event record. Proposed lending initiatives and practical actions are not announced commitments.
[31] Event reflection by Simba Magumise on LinkedIn, supplied as a screenshot dated 4 November 2026; no public post URL provided. Speaker remarks are paraphrases of this attendee account, not transcript quotations. The official event page independently confirms the panel.
Oui Capital’s executive summary describes cross-border payments, while its market discussion describes formal and informal remittances. This scope ambiguity limits comparison with other datasets. PAPSS’s 1,000% figure measures transaction count growth, not value or market share; the release does not disclose an absolute baseline or exact comparison dates.
AXIAN registrations do not count unique newly included people. Its Mastercard announcement does not verify rollout of every product in every country. African Development Bank programme targets must not be added together as unique beneficiaries. Verto’s annual figure is the scale reported in October 2025, not a calendar-year 2025 total. Vault22’s institution coverage is a capability measure; individual connections can be temporarily unavailable. No comparable, verified lending or income outcomes are claimed for the three companies.